Posts

Let's keep the Eurozone together. Really?

During the recent negotiations between Greece and its creditors about a debt restructuring programme, we learned that both parties were very keen on maintaining the Eurozone intact (aka Greece staying in the Eurozone). Why is it in their interests to do so? Let's see both sides arguments. First the Greek argument. The Greeks are going through incredibly harsh times with sky-high unemployment and plummeting income, so it's fair to wonder why they are so keen on staying in the Eurozone. What is so great about the Euro that a country is ready to face the threat of economic collapse to stay in it? Indeed what is happening in Greece now, with all banks being closed, capital controls and cash redrawal close to impossible, is a financial collapse similar to the one the U.S. had feared after Lehman Brothers  bankruptcy. With no lending, an economy cannot function properly, companies face liquidity crisis leading to being shut down, people don't invest or rather emigrate and the...

French industry's competitiveness

The Gallois report about the French industry's competitiveness has just been made public (links here ) and received a lot of publicity from the French media. As a trained economist and French patriot, I was eager to read it. The author, a respected businessman - formerly head of aerospace giant EADS -  describes rather briefly the declining state of the French industry over the last ten years, which accounted for 18% of GDP in 2000 and is now down to 12.5%. What are the causes of this decline? The author cites various causes, ranging from product quality, technology, labour flexibility, cost, competition, education and regulation. Standard economic theory says the government should increase labour flexibility, promote competition, support education and enact smart regulation. For example, the Porter Hypothesis (cf Ambec et al 2011 ) states that market-friendly environmental policy can enhance business competitiveness through innovation. What are the main propositions? Create...

Economics Nobel Prize 2012

Image
The Nobel Prize in Economics has been awarded to US economists Lloyd Shapley and Alvin Roth for their work on market design . Market design is a subfield of microeconomics that studies how to make markets work efficiently. By efficiently (also called Pareto efficiency), economists mean that the outcome (in terms of who gets what in the market) cannot be improved without making at least one person worse off. Most often this outcome can be achieved by letting people freely trade goods using money as a means of exchange. However, there are some cases where money cannot be used. For example, Alvin Roth studied the market for kidney transplants where buying kidneys is not allowed on ethical grounds. By creating a database of likely donors and patients along with an algorithm to match them, his work allowed to increase the number of transplants and therefore of lives saved. Below is a lecture from Alvin Roth where he explains this case and other applications of market design: At a time...

Ben Bernanke about Quantitative Easing

Yesterday, the US Federal Reserve Chairman Ben Bernanke gave an argumented speech in defense of Large Scale Asset Programs (also called Quantitative Easing in the Financial jargon) initiated in 2009 and that have been since then continued and expanded. Being a former academic researcher, Professor Bernanke was very careful in explaining his vision and his speech was both nice to read and very informative. What are the Large Scale Asset Programs? The role of LSAP is to continue easing financial conditions in the economy when the Central Bank's benchmark rates have reached the zero lower bound. This program is called unconventional because it lacks a standard model explaining why and how it should be used, and has been little used in history. It consists in letting the Central Bank purchase government assets (Treasury boons, or bonds issued by government sponsored agencies) so as to reduce the yield of such assets.  Quantitative evidence Econometric evidenc...

Book review: soccernomics

Image
I just finished reading the fascinating book "SOCCERNOMICS: why England loses, why Spain, Germany and Brazil win, and why the US, Japan, Australia, Turkey - and even Iraq - are destined to become the kings of the World's most popular sport" . It is the first time I ever read anything interesting about football! The authors, Simon Kuper and Stefan Szymanski, are two economists interested in sports and they enjoy to apply - in sometimes an unconventional and surprising way - their economist's tools and reasoning to sports. Using plenty of data, they try to answer the following questions: Why do clubs have so much debt? Is a club a business? How efficient is the transfer market? Should we regulate more the sports markets? aka limit debt, share the revenues more equally among clubs Is it worth hosting a major sports event like the World Cup or the Olympics? How to shoot a penalty? What does the rise and decrease of some clubs tell us? Rather t...

Stylized facts on financial frictions

Image
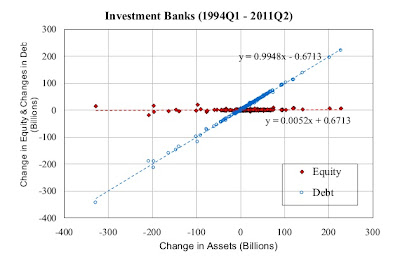
In a paper presented at the National Bureau of Economic Research (NBER) Macro Annual Conference (April 20-21, 2012), Adrian, Colla and Song Shin (2012) present four stylized facts about financial frictions: In a contraction, bank loans are reduced but bond financing increases to make up for most of the gap. For example, during the 2007-2009 crisis, the number of bank loans issued in the USA declined by 75% whereas the number of bonds increased by two fold. Credit spreads (= risk premium) increase in a contraction Bank lending changes dollar for dollar with a change in debt, with equity being "sticky". So, credit supply by banks is the consequence of their choice of leverage. (cf. figure 1 and 2) Bank leverage is procyclical figure 1: Investment Banks: change in equity and debt in relation to the change in assets figure 2: Commercial Banks: change in Equity and Debt in relation to a change in assets They then develop a model of financial intermediation that...

Bernanke lectures - The Federal Reserve and the financial crisis

Image
In March, the Chairman of the Federal Reserve (ie the US Central Bank) gave a series of four lectures about the Federal Reserve system and the Financial Crisis to students of Georges Washington University. I have enclosed the videos of these classes. Dr. Bernanke, who is also a prominent academic researcher, is very skilled at explaining very complex problems with easy words. So, even non economists will find these lectures accessible and useful to understand the sequence of events that led to a global financial crisis and how the Federal Reserve responded to it. Let me give you a few extracts and comments that I found particularly worth highlighting: The three pillars of central bank action are: Monetary policy (setting interest rates) Provision of liquidity (lender of last resort) Financial regulation and supervision (shared with other agencies) "We did not foresee that declining house prices would trigger a financial crisis." This is an honest but clear ...